 Recruit


Summary: If a business creates permanent establishment in a foreign country that generates local revenue, then the foreign country (or host country for that business) can impose local corporate taxes on that business.
A permanent establishment (PE) is a tax concept under OECD Article 5 that gives a country the right to tax the corporate profits a foreign company earns through a fixed presence or dependent agent on its territory. The four classic types are fixed-place PE (office, branch, factory), agency PE (employees with contract authority), service PE (in-country service performance), and construction PE (long-running building projects). Triggering a PE means filing corporate tax returns in that country, even without an entity.
What Is Permanent Establishment Risk?
Permanent establishment risk is the probability that a company’s cross-border activities (people, contracts, services, or premises) will be deemed by a foreign tax authority to constitute a PE, with the corresponding obligation to register, file local corporate tax returns, and pay corporate income tax. The risk is not theoretical: HMRC, Bundeszentralamt fur Steuern, the French DGFiP, and the Indian revenue service all run regular PE audits.
Permanent establishment risk lives on a spectrum. Sending an SDR to attend a trade show in another country is low risk. Letting a senior salesperson sign customer contracts from a home office abroad is high risk. Most modern PE risk in remote-first companies sits in the middle: a long-tenured employee performing core revenue-generating work from a country where the company has no entity. The middle is where most surprises happen.
Why Permanent Establishment Matters
Permanent establishment is the rule that decides whether a country can tax your corporate profits. If you have no PE, the country has no taxing right over you (with limited exceptions). If you trigger a PE, you have to register, file local corporate income tax returns, allocate global profit to the local PE, and pay tax there.
The headline cost is corporate income tax on the profits attributable to that PE. The hidden costs are bigger: registration filings, local accounting, transfer-pricing documentation, treaty-claim paperwork, late-filing penalties, and the risk that two countries both tax the same profit. For a small startup that “just hired one engineer in Germany,” an inadvertent PE can mean six figures of unbudgeted cost and several quarters of remediation work.
The Four Classic Types of Permanent Establishment
1
Fixed-Place PE
The traditional definition: a fixed place of business through which the enterprise carries on its activities. Office, branch, factory, workshop, mine, oil well, quarry. Article 5(2) of the OECD model treaty lists examples. Renting an office in a country and staffing it with employees almost always creates a fixed-place PE.
2
Agency PE
Even without a fixed place, you can have a PE if a person in the country acts as a “dependent agent” with authority to conclude contracts in your name. A senior salesperson with contract-signing authority based in Germany triggers German agency PE for the foreign-headquartered company, even if there is no German office. The 2017 BEPS Action 7 revision broadened this further to include people who “habitually play the principal role leading to the conclusion of contracts.”
3
Service PE
Some countries (often via bilateral treaty) treat extended service-delivery as a PE even without a fixed place. India’s standard treaty applies a service PE if a foreign company performs services in India for more than 183 days in any twelve-month period. The US-Canada treaty has similar rules.
4
Construction PE
A building site, construction, installation, or assembly project that lasts longer than a treaty-specified threshold (usually 6 or 12 months) constitutes a PE. Common in oil and gas, infrastructure, and large industrial projects.
The Five Practical Triggers In Modern Remote-First companies
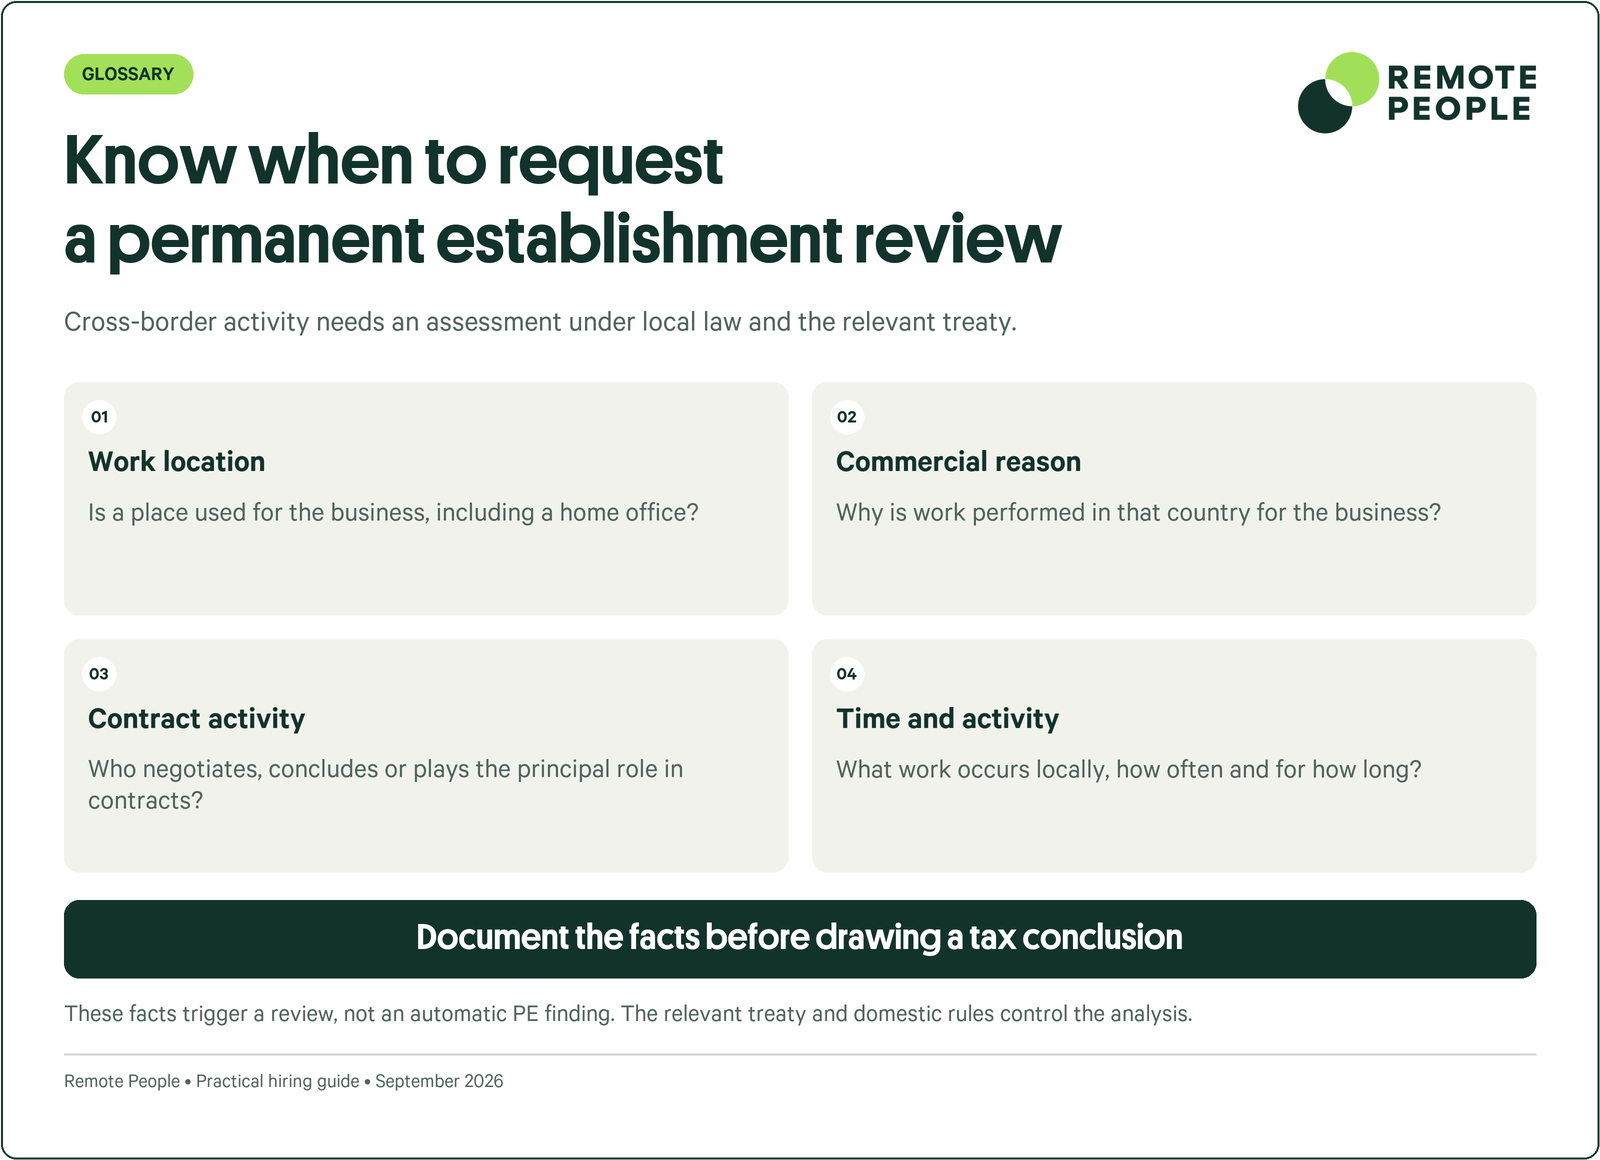
Most early-stage tech companies do not own factories or run construction sites. The PE risks they actually face come from people, not places.
Trigger 1: Senior employee with contract-signing authority abroad. A VP Sales who lives in London and signs UK customer contracts on behalf of the US-headquartered parent triggers UK agency PE. The fix is usually re-routing contract signing to a US-resident officer, or employing the VP Sales through a UK entity (own subsidiary or EOR).
Trigger 2: Long-term assignee. An engineering manager from US headquarters who relocates to Germany for 18 months can pull a fixed-place PE into Germany if they manage a local office or perform core revenue-generating activities there.
Trigger 3: Sales reps with implicit authority. Even without formal signing authority, a person who “habitually plays the principal role leading to the conclusion of contracts” can trigger agency PE under post-BEPS rules. Quote-and-close salespeople in country are higher risk than purely top-of-funnel SDRs.
Trigger 4: In-country support of long-term services. A US SaaS company sending engineers to a customer site in India for an 18-month implementation can create service PE.
Trigger 5: WFH employee performing core functions. Less settled, but tax authorities are increasingly arguing that an employee’s home office, used as a regular workspace for core revenue-generating activities, can itself be a fixed place of business. Spain, Israel, and the UK have all run cases on this.
PE Risk By Country
| Country | PE risk profile | Notes |
|---|---|---|
| United Kingdom | Medium-high | HMRC active on agency PE for sales reps; home-office cases growing. UK statutory PE definition tracks OECD closely. |
| Germany | High | Active enforcement, particularly for sales-led trigger. Home-office can constitute Betriebsstätte under specific circumstances. |
| France | High | French tax authority is among the most aggressive on agency PE for senior sales staff. |
| India | High | Service PE threshold of 183 days is easy to cross. Indian revenue authority is litigious. |
| Australia | Medium | ATO MAAL (Multinational Anti-Avoidance Law) extends PE-equivalent rules to certain digital-economy structures. |
| Singapore | Medium-low | IRAS publishes clear PE guidance; 183-day threshold for service PE in standard treaties. |
| Spain | Medium-high | Spanish tax authority has run several home-office and dependent-agent PE cases against US tech firms. |
| United States (inbound) | Medium | US “trade or business” + treaty PE concept. Enforcement varies; safe harbours for limited activity. |
Practical Mitigations
Five mitigations that reduce PE risk without giving up the international hire.
1. Restrict contract authority. Limit signing authority to officers based in the home country. Document this in board minutes and the employee’s offer letter. If the salesperson cannot sign, agency PE is much harder to establish.
2. Use auxiliary or preparatory exemption. Article 5(4) of the OECD model treaty exempts certain “preparatory or auxiliary” activities from creating a PE: storage, display, purchasing, information gathering. The exemption has narrowed under BEPS but still useful for limited activities.
3. Local entity for core activities. If a country crosses 5+ employees, particularly with revenue-generating roles, set up a local entity, employ the team locally, and pay the local corporate tax cleanly rather than face an inadvertent PE finding.
4. Employer of record. An employer of record employs the person in their country, runs payroll, and shoulders the local employment compliance. The EOR does not entirely eliminate PE risk on its own (the principal still has commercial activity in country) but it removes the employer-side trigger and gives the principal a documented arrangement that reduces the practical exposure.
5. PE risk review. Big-4 firms (PwC, KPMG, Deloitte, EY) all offer formal PE risk reviews. Worth doing before scaling international headcount past 5 in any single country.
What Happens If You Trigger A PE You Didn't Expect
The remediation path depends on how the issue surfaces.
Self-discovered. You realise during a tax-counsel review that an arrangement (typically a senior sales hire abroad) probably triggers PE. Voluntary disclosure usually attracts lower penalties than waiting to be assessed. Engage local tax counsel, file the late corporate tax returns, allocate profit, and negotiate.
Audit-found. The foreign tax authority initiates an audit and identifies the PE. Penalties for unfiled returns, interest on late tax, and a longer remediation timeline. Big-4 PE risk reviews typically prevent this if commissioned early.
Treaty-based remediation. If the principal country and the host country both have a treaty, the mutual-agreement procedure (MAP) allows the two competent authorities to negotiate which country has primary taxing rights. MAP cases run 18-36 months but usually avoid double taxation in the end.
The cost of remediation, even when handled well, typically runs 3-10x what it would have cost to structure correctly upfront. The lesson is to do the PE risk review before scaling international headcount, not after.
The EOR-Led Structuring Approach
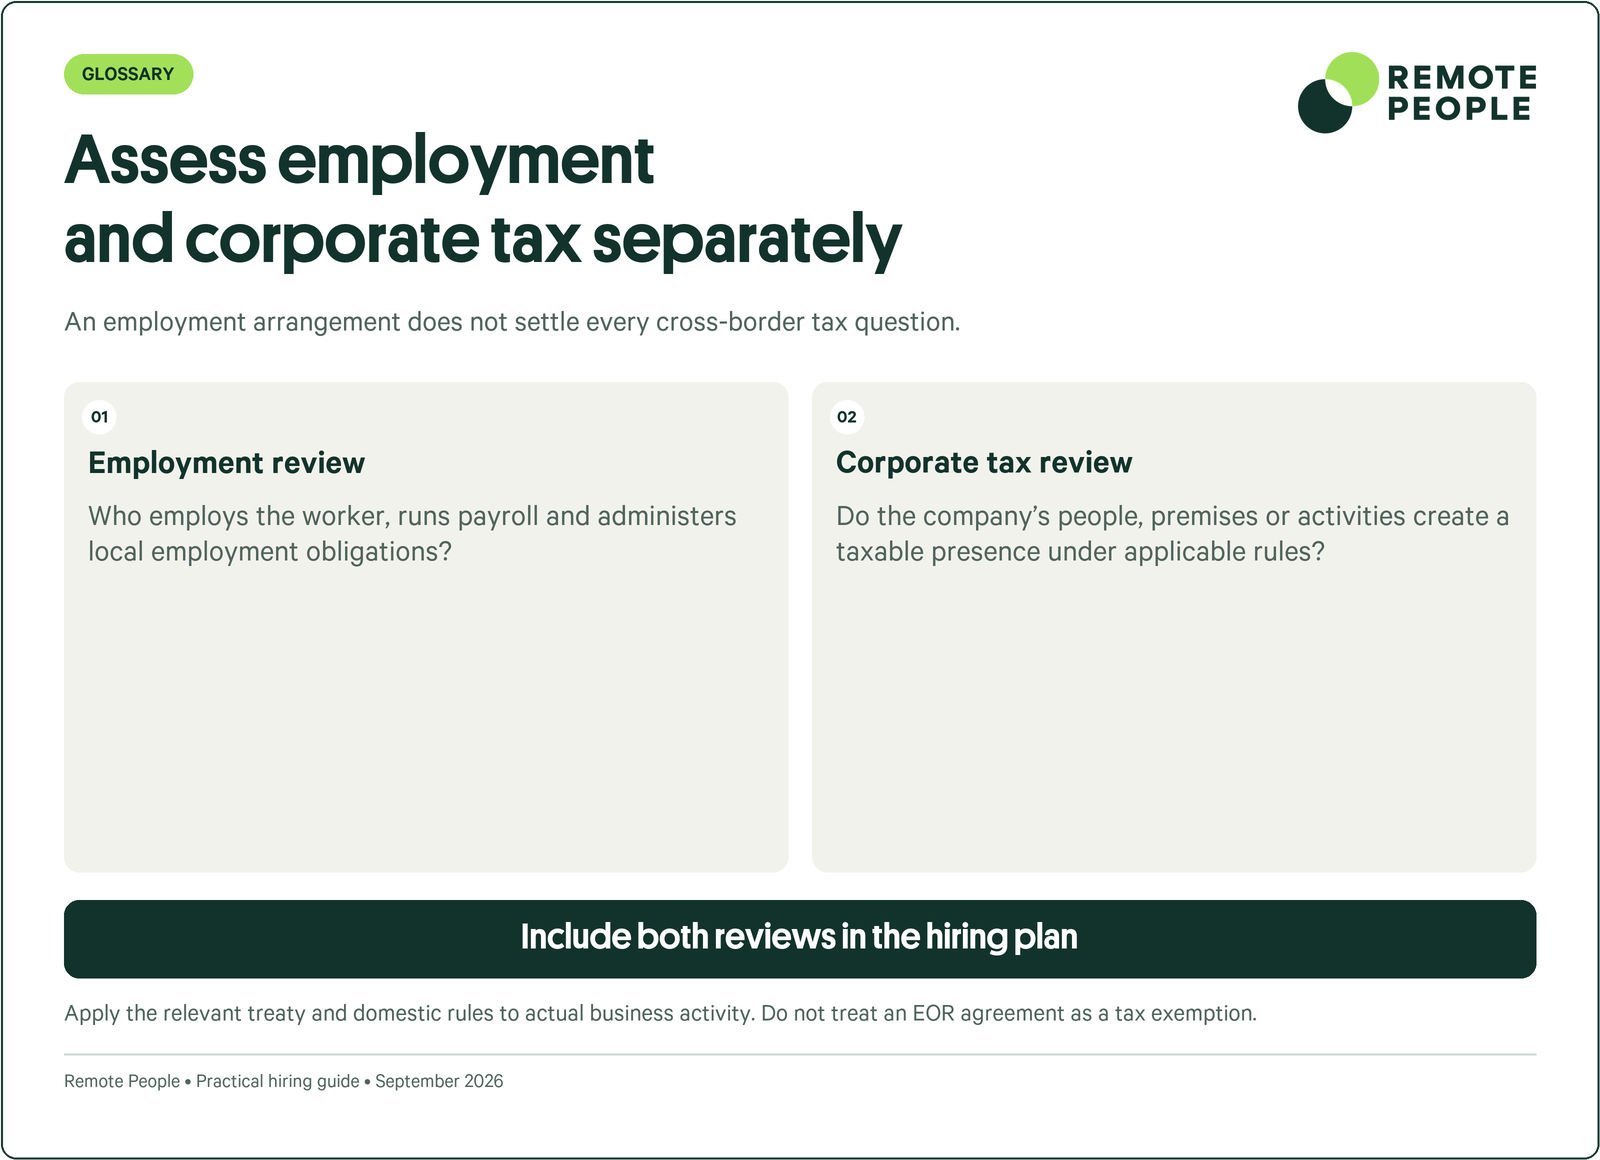
For most early-stage cross-border hiring, an EOR is the practical first line of defence. The EOR is the legal employer in the country where the worker lives, runs local payroll, withholds tax, and remits social charges. The EOR contractually carries the employer-side of the relationship, reducing the principal’s exposure on agency-PE, fixed-place-PE, and service-PE arguments.
EOR is not a magic eraser. If the principal’s salespeople sign contracts in country, or if the principal performs services through subcontractors there, PE risk can still arise from the principal’s own activity. But for most engineering, support, and back-office hires, an EOR materially reduces the PE conversation.
Once a country crosses 20-50 employees with multi-year horizon, switching from EOR to a wholly-owned subsidiary becomes the right call: corporate tax is paid cleanly through the subsidiary, and the EOR layer (and its monthly fee) drops away.
Decision Framework
Five questions to scope PE risk before hiring abroad.
- What does the role actually do? Sales with contract authority is highest risk. Engineering and support, lowest. Senior managers with strategic authority, medium-high.
- How long is the engagement? Service PE thresholds are usually 183 days. Construction PE 6-12 months. Long-term assignments compound risk.
- What does the bilateral treaty say? US-UK, US-Germany, US-India, US-Brazil all have different specific PE thresholds and exemptions. Read Article 5.
- Do we have an entity in the country? If yes, employ locally. If no, EOR is the practical bridge.
- What’s the headcount horizon? 1-5 in country: EOR. 5-20: EOR or starting to evaluate entity. 20+: subsidiary becomes the right call.
Hiring across borders and worried about permanent establishment risk? Our employer of record service employs your team in 150+ countries, runs local payroll, and gives you a documented employer-of-record arrangement that materially reduces your practical PE exposure. Pair with proper tax counsel on the principal’s commercial activity and you have a defensible structure.
Frequently Asked Questions
A permanent establishment (PE) is a tax concept under OECD Article 5 that gives a country the right to tax the corporate profits a foreign company earns through a fixed presence or dependent agent on its territory. The four classic types are fixed-place PE (office, branch, factory), agency PE (employees with contract authority), service PE (in-country service performance), and construction PE (long-running building projects).
Permanent establishment risk is the probability that a company's cross-border activities will be deemed by a foreign tax authority to constitute a PE, with the resulting obligation to register, file local corporate tax returns, and pay corporate income tax. HMRC, the German Bundeszentralamt fur Steuern, the French DGFiP, and the Indian revenue service all run regular PE audits.
Fixed-place PE (a physical place of business: office, branch, factory, workshop), agency PE (a person in country who habitually concludes contracts in your name), service PE (extended in-country service delivery, typically over 183 days), and construction PE (a building or installation project lasting longer than 6-12 months under most treaties).
Five practical triggers in modern remote-first companies: (1) senior employee with contract-signing authority abroad, (2) long-term assignee performing core activities, (3) sales reps with implicit authority who play the principal role in concluding contracts, (4) in-country support of long-term services, and (5) WFH employee performing core revenue-generating activities (newer area, contested across jurisdictions).
An employer of record significantly reduces but does not entirely eliminate PE risk. The EOR is the legal employer in country, runs payroll, and shoulders local employment compliance. The principal still needs to manage its own commercial activity (contract signing, services delivered) to avoid creating a PE on its own account. EOR is the practical first line of defence; pair with proper tax counsel for high-risk roles.
France, Germany, India, and Spain rank high for active enforcement. The UK is medium-high and rising on home-office cases. Australia uses MAAL (Multinational Anti-Avoidance Law) for digital-economy structures. Singapore and most of Latin America (excluding Brazil) sit at medium-low risk. The US is medium for inbound cases. Always check the bilateral treaty for specific PE thresholds.
Remediation paths: self-discovery via tax-counsel review (lowest penalties, voluntary disclosure), audit-found by the foreign tax authority (higher penalties and interest), or treaty-based mutual-agreement procedure (MAP, 18-36 months, usually avoids double taxation). Total remediation cost typically runs 3-10x what proper upfront structuring would have cost. Run a PE risk review before scaling, not after.
Direct cost: corporate income tax on profits attributable to the PE, plus filing penalties and interest. Indirect cost: registration filings, local accounting, transfer-pricing documentation, treaty-claim paperwork, late-filing penalties, and risk of double taxation. For an unprepared startup, an inadvertent PE often runs into six figures of unbudgeted cost plus several quarters of remediation work.
Andrew (Drew) joined the Remote People team in 2020 and is currently Director, Regulatory Affairs. For the past 13 years, he has been a trusted advisor to C-Suite executives and government ministers on international compliance and regulatory issues. Drew holds a law degree from the University of Otago, a PhD from the University of Sydney, and is an enrolled Barrister and Solicitor of the High Court of New Zealand.
